You are using an out of date browser. It may not display this or other websites correctly.
You should upgrade or use an alternative browser.
You should upgrade or use an alternative browser.
Customs charges
- Thread starter bonehead
- Start date

the_greeze
User
system11 said:How is this news to people, have you been living under rocks? It's been this way for over a decade.
The only recent change was the pound losing value so some correctly declared DVDs and so on just tipped past the £15 mark.


Agreed. I would always ask the seller to mark the items as low as possible to avoid charges. Purchased a major havoc control panel and roller last year and got stung almost £100 in charges. It's a disgrace it can be done to that extent.
This is why I had the wg6100 covers made in the uk.
I might even look at getting control panels made over here and sell them. Everything is cheap in the US but the customs make it almost pointless!!!!!!!
This is why I had the wg6100 covers made in the uk.
I might even look at getting control panels made over here and sell them. Everything is cheap in the US but the customs make it almost pointless!!!!!!!

Baiterhater
Active member
- Credits
- 73CR
well i recently had the opposite 300 dollars worth from arcade shop and the charge was £18.00 i was well chuffed
j
j

I didn't know the min was now £15, I thought it was still £50, I guess I have been living under a rock.
The application of charges has always seemed a bit random to me, seen some shipments worth well over $150 with no charges and have seen massive charges on much cheaper stuff. I always assume I'm going to get whacked with some extra charges so treat the times I don't as a result
The application of charges has always seemed a bit random to me, seen some shipments worth well over $150 with no charges and have seen massive charges on much cheaper stuff. I always assume I'm going to get whacked with some extra charges so treat the times I don't as a result
I would not mind paying the VAT, its just in a lot of case you can't pay that as its a private sale, its the £8-£10 handling charge by the delivery companies that annoy me.
Tis true though the $/£ exchange rate has made things even closer to the bone in terms of not getting much for you buck.
Tis true though the $/£ exchange rate has made things even closer to the bone in terms of not getting much for you buck.

Don't get me started on this....
For small value items (over 15$) we are paying 2 or 3 times the costs of the item. VAT is supposed to be 20%, so someone is on the gravy train here....
I have just ordered two items from the US - both values around 10$. Rather than add them to a single order to save postage, I've ordered them separately and paid postage twice - as this is likely to be cheaper than the handling charges of a 20$ package.
I think a lot of folk post brexit are in for very rude awakening when similar charges might start to hit EU imports - but that's a separate rant....

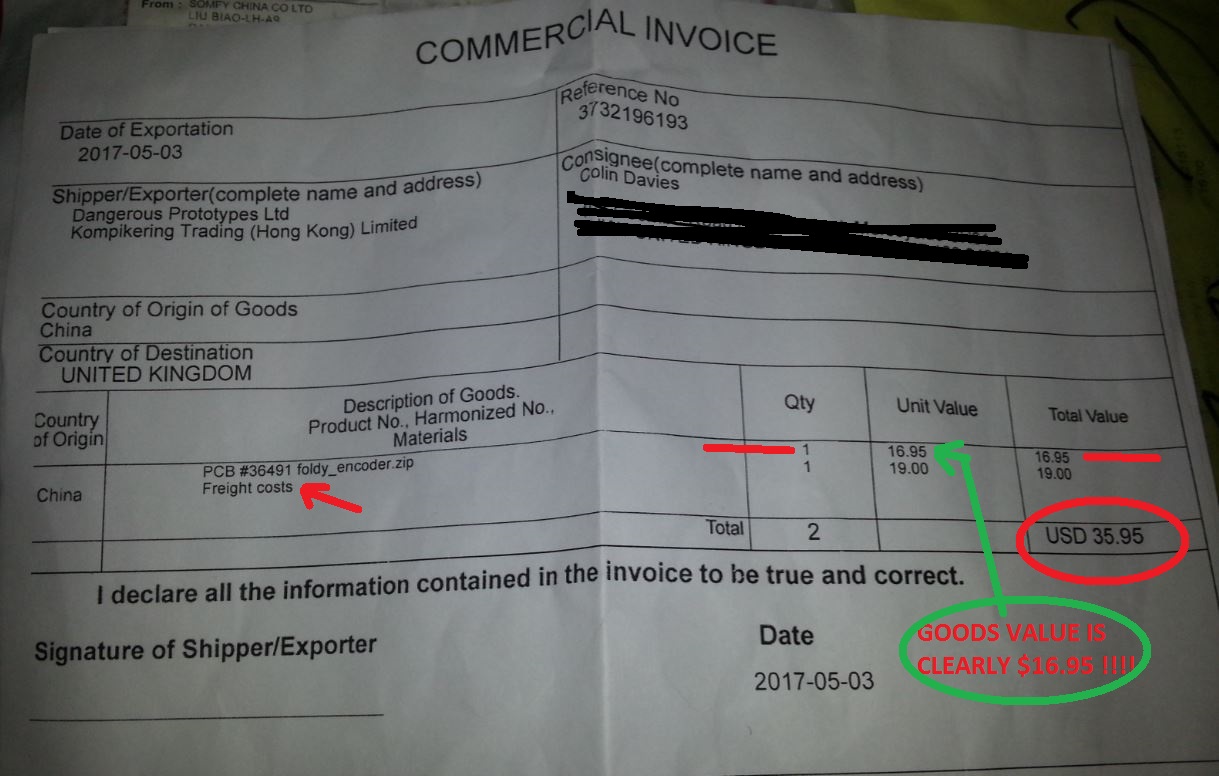
Here we go..... any numbskull can see the goods value and also the freight charges.... DHL just say that the total invoice value is £28 ($36.95) so charged me £10 + £6 Vat !! even though it says on their website items under £15 (excluding shipping) are free of charges.... !!
Also.... Note that DHL sent me the invoice when it was sent out from China, before it had even been near UK Customs. So obviously someones on a bonus to snag stuff who can't read !!!
ColinD2017-05-14 22:04:17
Also.... Note that DHL sent me the invoice when it was sent out from China, before it had even been near UK Customs. So obviously someones on a bonus to snag stuff who can't read !!!
ColinD2017-05-14 22:04:17
BarrySlisk
Active member
"I think a lot of folk post brexit are in for very rude awakening when similar charges might start to hit EU imports - but that's a separate rant...."
It would not surprise me if UK got a better deal than EU. Besides you can't put a price on.....FREEEDOM !!!!
BarrySlisk2017-05-14 22:27:19
It would not surprise me if UK got a better deal than EU. Besides you can't put a price on.....FREEEDOM !!!!
BarrySlisk2017-05-14 22:27:19
I argued he charges and ups gave me an email address for customs which then over turned ups charges and made them post it to me free of charges.
Ups charge £12 just for their paperwork!!!
As regards brexit if we pay charges for Eu I'm ports so will they buying from us.
Let's leave brexit for another discussion time.
Keep on gaming.
Ups charge £12 just for their paperwork!!!
As regards brexit if we pay charges for Eu I'm ports so will they buying from us.
Let's leave brexit for another discussion time.
Keep on gaming.

I had an invoice from DHL for a parcel that had already been delivered from play-Asia. I was being well overcharged so rang gov website for some advice and then wrote to DHL. Never heard back and didn't get a revised invoice so didn't pay anything. I think they try it on hoping people will just pay it. They are pocketing the money themselvesneo-geo-mvs2017-05-14 23:36:01
Try this.... it says there is no duty to pay on my pcb's valued at $16.95... Only works once though then you have to pay !!
www.dutycalculator.com
This one works... but you have to put the prices in the local currency and also estimate the handling fee in euros....
http://importcalculator.com/
Notice its its 22 euro's (but should be £15)
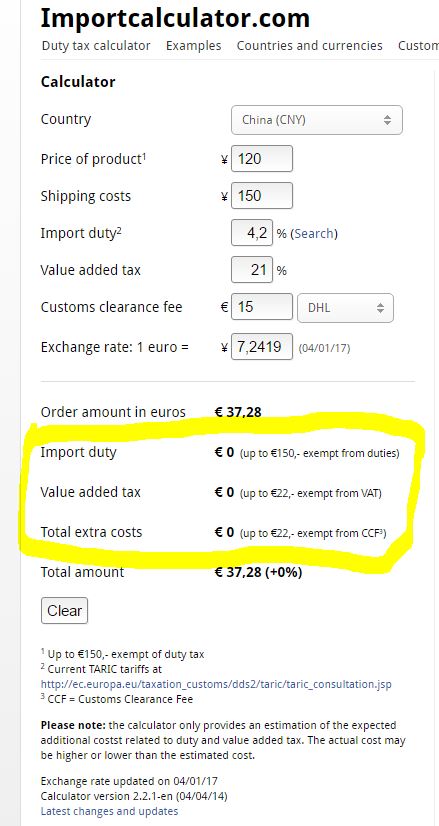
ColinD2017-05-19 18:03:59
www.dutycalculator.com
This one works... but you have to put the prices in the local currency and also estimate the handling fee in euros....
http://importcalculator.com/
Notice its its 22 euro's (but should be £15)
ColinD2017-05-19 18:03:59
BarrySlisk said:"I think a lot of folk post brexit are in for very rude awakening when similar charges might start to hit EU imports - but that's a separate rant...."
It would not surprise me if UK got a better deal than EU. Besides you can't put a price on.....FREEEDOM !!!!
The charges are based on your VAT rate, government is very unlikely to raise the personal import allowance when leaving the customs union turns into a cash cow.
Quite often people will f**k up on currency conversion though - I've claimed back on this a few times now. How hard is it to tell £ from Y or $?
system112017-05-19 18:16:04
2 What are the limits for customs duty and import VAT?
The limits for customs duty and import VAT are:
- commercial consignments, that is, goods you have purchased, of £15 or less are free from Customs Duty and import VAT. Note: This doesn’t include alcohol, tobacco products, perfume or toilet waters, these items are excluded from the relief of duty and VAT at import. In addition, commercial consignments sent to the UK from the Channel Islands don’t benefit from any relief of import VAT
- if you’re sent a gift with a value of £39 or less, which complies with the rules shown in paragraph 2.4, it will be free from Customs Duty and import VAT (gifts of alcohol, tobacco, perfumes and toilet waters are subject to the limits shown in paragraph 2.5, while gifts of perfumes and toilet waters are subject to the limits in paragraph 2.6)
- Customs Duty becomes payable if the value of the goods is over £135
| Goods Value* | Customs Charges applicable |
|---|---|
| £0.01 to £15 | - No customs duty - No Import VAT** |
| £15.01 to £135 | - No customs duty - Import VAT due |
| £135.01 and greater | - Customs duty due, - Import VAT due |
There are a number of other circumstances where relief from some or all customs charges may be available. If you think your goods may be eligible for a relief you can contact the HM Revenue and Customs (HMRC) Customs, International Trade and Excise enquiries service by phone on 0300 200 3700 for further information.
Further ways to contact HMRC for general advice and information on imports can be found on the GOV.UK website.
Gifts
Goods sent as a gift that are over £39 in value are liable to import VAT, Customs Duty also becomes payable if the value of the goods is over £135.
To qualify as a gift:
- the customs declaration must be completed correctly
- the gift must be sent from a private person outside the EU to a private person(s) in this country
- there is no commercial or trade element and the gift hasn’t been paid for either directly or indirectly by anyone in the UK
- the gift is of an occasional nature only, for example, for a birthday or anniversary
ColinD2017-05-19 18:24:57

I always ship stuff back from Japan in batches - i try to keep boxes for expensive stuff small and cheap stuff big. Also I find SAL & SEA almost always get customs charges. Single items sent by EMS seem to get through ok.
I do resent paying parcelforce £8 for sending me the customs bill though.
I do resent paying parcelforce £8 for sending me the customs bill though.